Can You Scrap a Car That Still Has Finance?
Find out how to scrap a car with outstanding finance in Essex

Scrapping a car that still has finance on it is possible, but you need to handle it correctly.
If you are still making payments on your vehicle, the finance company may legally own it, which means you cannot simply hand it over to a scrap yard without dealing with that debt first.
Understanding your position before you arrange collection could save you from serious legal and financial trouble.
This guide walks you through everything you need to know about scrapping a financed car in Essex, from checking whether you legally own the vehicle to settling your balance and getting paid on the same day.
What does it mean to scrap a car with outstanding finance?
Outstanding finance simply means you still owe money on a loan or credit agreement that was used to purchase the vehicle.
Until that balance is cleared, the car may not be legally yours to sell or scrap.
This is a situation many drivers in Essex find themselves in, especially when a vehicle becomes unroadworthy or too expensive to repair.
The type of finance agreement you have matters a great deal here. With a Personal Contract Purchase (PCP), the finance company retains ownership of the car throughout the agreement.
You are essentially paying to use the vehicle, with the option to buy it outright at the end by paying a final lump sum known as the balloon payment.
With Hire Purchase (HP), ownership transfers to you only once you have made every scheduled payment.
A personal loan is different, because you borrow money from a bank or lender and immediately become the legal owner of the car, even though you still owe the debt.
Knowing which type of agreement you have tells you whether you need the finance company's permission before you can scrap the vehicle.
If you are on PCP or HP, you almost certainly do. If you used a personal loan, the process is simpler, though the debt still needs to be cleared.
Do you legally own a car that's still on finance?
In most cases, no. With PCP and HP agreements, the finance company retains legal title to the vehicle until the final payment clears.
This is a standard condition written into nearly every finance agreement in the UK, and it is governed by the Consumer Credit Act 1974.
The car appears in your name on the V5C logbook, but that document only confirms who is the registered keeper, not who owns the vehicle outright.
This distinction is critically important when it comes to scrapping. Only the legal owner of a vehicle has the right to authorise its destruction.
If you scrap a car without permission from the finance company that legally owns it, you are disposing of an asset that does not belong to you. That can have very real consequences.
Many people are genuinely surprised to learn they do not own the car they have been driving for two or three years.
The finance industry in the UK is built on this model, and it is entirely legal. However, it does place a responsibility on you to be transparent about your situation before arranging anything with a scrap service.
What happens if you scrap a financed car without settling the debt?
Scrapping a car that you do not legally own, without the finance company's knowledge or consent, can be treated as fraud.
The finance company still holds legal ownership, and by authorising the destruction of that vehicle, you would be depriving them of an asset they have a legal claim to. In serious cases, this could lead to criminal charges under the Fraud Act 2006.
Even in less serious situations, the financial consequences can be significant.
You would still owe the remaining balance on your finance agreement, and the finance company would likely pursue that debt regardless of what happened to the vehicle.
You might also find it harder to obtain credit in the future, as this type of default leaves a mark on your credit record.
The practical advice here is straightforward: speak to your finance provider before you do anything else.
They deal with early settlements regularly and will give you a clear figure to aim for.
Avoiding that conversation will not make the debt disappear, but it could make your situation much harder to resolve.
How to check if your car has outstanding finance
Before you contact a scrap service, it is worth confirming exactly what finance, if any, is attached to your vehicle.
This is especially useful if you bought the car second-hand and are not certain of its full financial history.
The most widely used method is an HPI check. HPI Ltd is an approved data provider that holds records of outstanding finance agreements, stolen vehicle reports, write-off history, and mileage discrepancies.
A basic check typically costs between £10 and £20 and can be completed online in minutes using your vehicle registration number.
The RAC and the AA offer similar vehicle history checks.
The Citizens Advice Bureau recommends running a check before any major vehicle transaction, and it is considered best practice across the used car industry.
If you already know you have an active finance agreement, you do not necessarily need to run a check, but it is still worth verifying the exact balance.
Log in to your finance provider's online portal, check your most recent statement, or call their customer service team to confirm the current settlement figure.
That figure is the amount you would need to pay today to close the agreement in full.
Steps to take before scrapping a car with finance
Contact your finance provider first
The first and most important step is to call your finance company directly. Let them know that you are considering scrapping the vehicle and ask about your options.
Most mainstream lenders, including those regulated by the Financial Conduct Authority (FCA), have clear processes in place for early settlement requests.
They cannot refuse your request to settle, but they may charge an early settlement fee depending on your agreement type.
Being upfront with your lender from the start protects you legally and gives you a clear picture of what the process will look like.
Do not arrange collection of the vehicle before you have had this conversation.
Request a settlement figure
A settlement figure is the exact amount of money needed to pay off your finance agreement in full at a given point in time. It is usually slightly less than the total remaining balance because it factors in a rebate of future interest charges.
Under the Consumer Credit Act, you are legally entitled to request a settlement figure at any time, and your lender must provide it within seven days.
Once you have that figure, you know exactly what you are working with. If the scrap value of your car is higher than the settlement figure, you will walk away with cash in hand. If the scrap value is lower, you will need to make up the shortfall before the agreement can be closed.
Use your scrap payment to settle the balance
This is where timing matters. Benfleet Scrap Co offers same-day bank transfers, which means the money from scrapping your car can land in your account on the day of collection.
That payment can then be used immediately to contribute to or fully cover your settlement figure.
If you are looking at your options right now, get an instant scrap quote to understand the value of your vehicle before you commit to anything. Having that number in hand before you call your lender makes the whole process much more straightforward.
Notify the DVLA once scrapped
Once your car has been legally scrapped, you are required to inform the DVLA. A reputable Authorised Treatment Facility (ATF) like Benfleet Scrap Co will issue a Certificate of Destruction (CoD), which confirms the vehicle has been disposed of responsibly and in line with UK regulations.
You should also update the DVLA directly so that the vehicle is removed from your name, protecting you from any future liability such as parking fines or road tax renewals.
For full guidance on this process, read our article on how to notify the DVLA when scrapping your car.
Can a scrap yard scrap your car without your consent?
No legitimate scrap yard will take a vehicle without the consent of the registered keeper or legal owner.
Any reputable ATF will ask for proof of identity and verify the ownership details before accepting a car for scrapping.
This protects both the customer and the business from becoming involved in fraudulent transactions.
If you have concerns about how scrap yards handle ownership verification, it is worth understanding your rights in full.
Read our detailed guide on can a scrap yard scrap your car without consent to see exactly how the process works and what safeguards are in place for consumers in Essex.

How much could you get for scrapping a financed car in Essex?
Scrap car values in Essex vary depending on the vehicle's make, model, weight, and the current price of scrap metal.
In 2026, the average scrap value for a typical family car in the UK sits somewhere between £150 and £400, though heavier vehicles or those with desirable parts can fetch more.
Benfleet Scrap Co offers a highest price guarantee in the region and provides free collection across Essex, so there are no hidden deductions on the day.
When you have an outstanding finance balance, the net amount you receive is the scrap payment minus what you owe.
For example, if your car is worth £300 in scrap and your settlement figure is £200, you would clear the debt and have £100 left.
If the settlement figure is higher than the scrap value, you would need to cover the difference yourself before the agreement can be closed and the vehicle legally released for scrapping.
To get a clearer idea of what your specific vehicle is worth before making any decisions, take a look at our guide on how much you'll get for scrapping your car.
Why choose Benfleet Scrap Co for your scrap car in Essex?
Benfleet Scrap Co has been serving Essex for over 40 years as a family-run business. That kind of history does not happen by accident.
It comes from consistently treating customers fairly, paying honestly, and handling every job with care and professionalism.
For someone dealing with the added complexity of a financed vehicle, working with a scrap service you can genuinely trust makes a real difference.
The business holds ISO 9001 and ISO 14001 certifications, which means both quality management and environmental standards are independently verified and regularly audited.
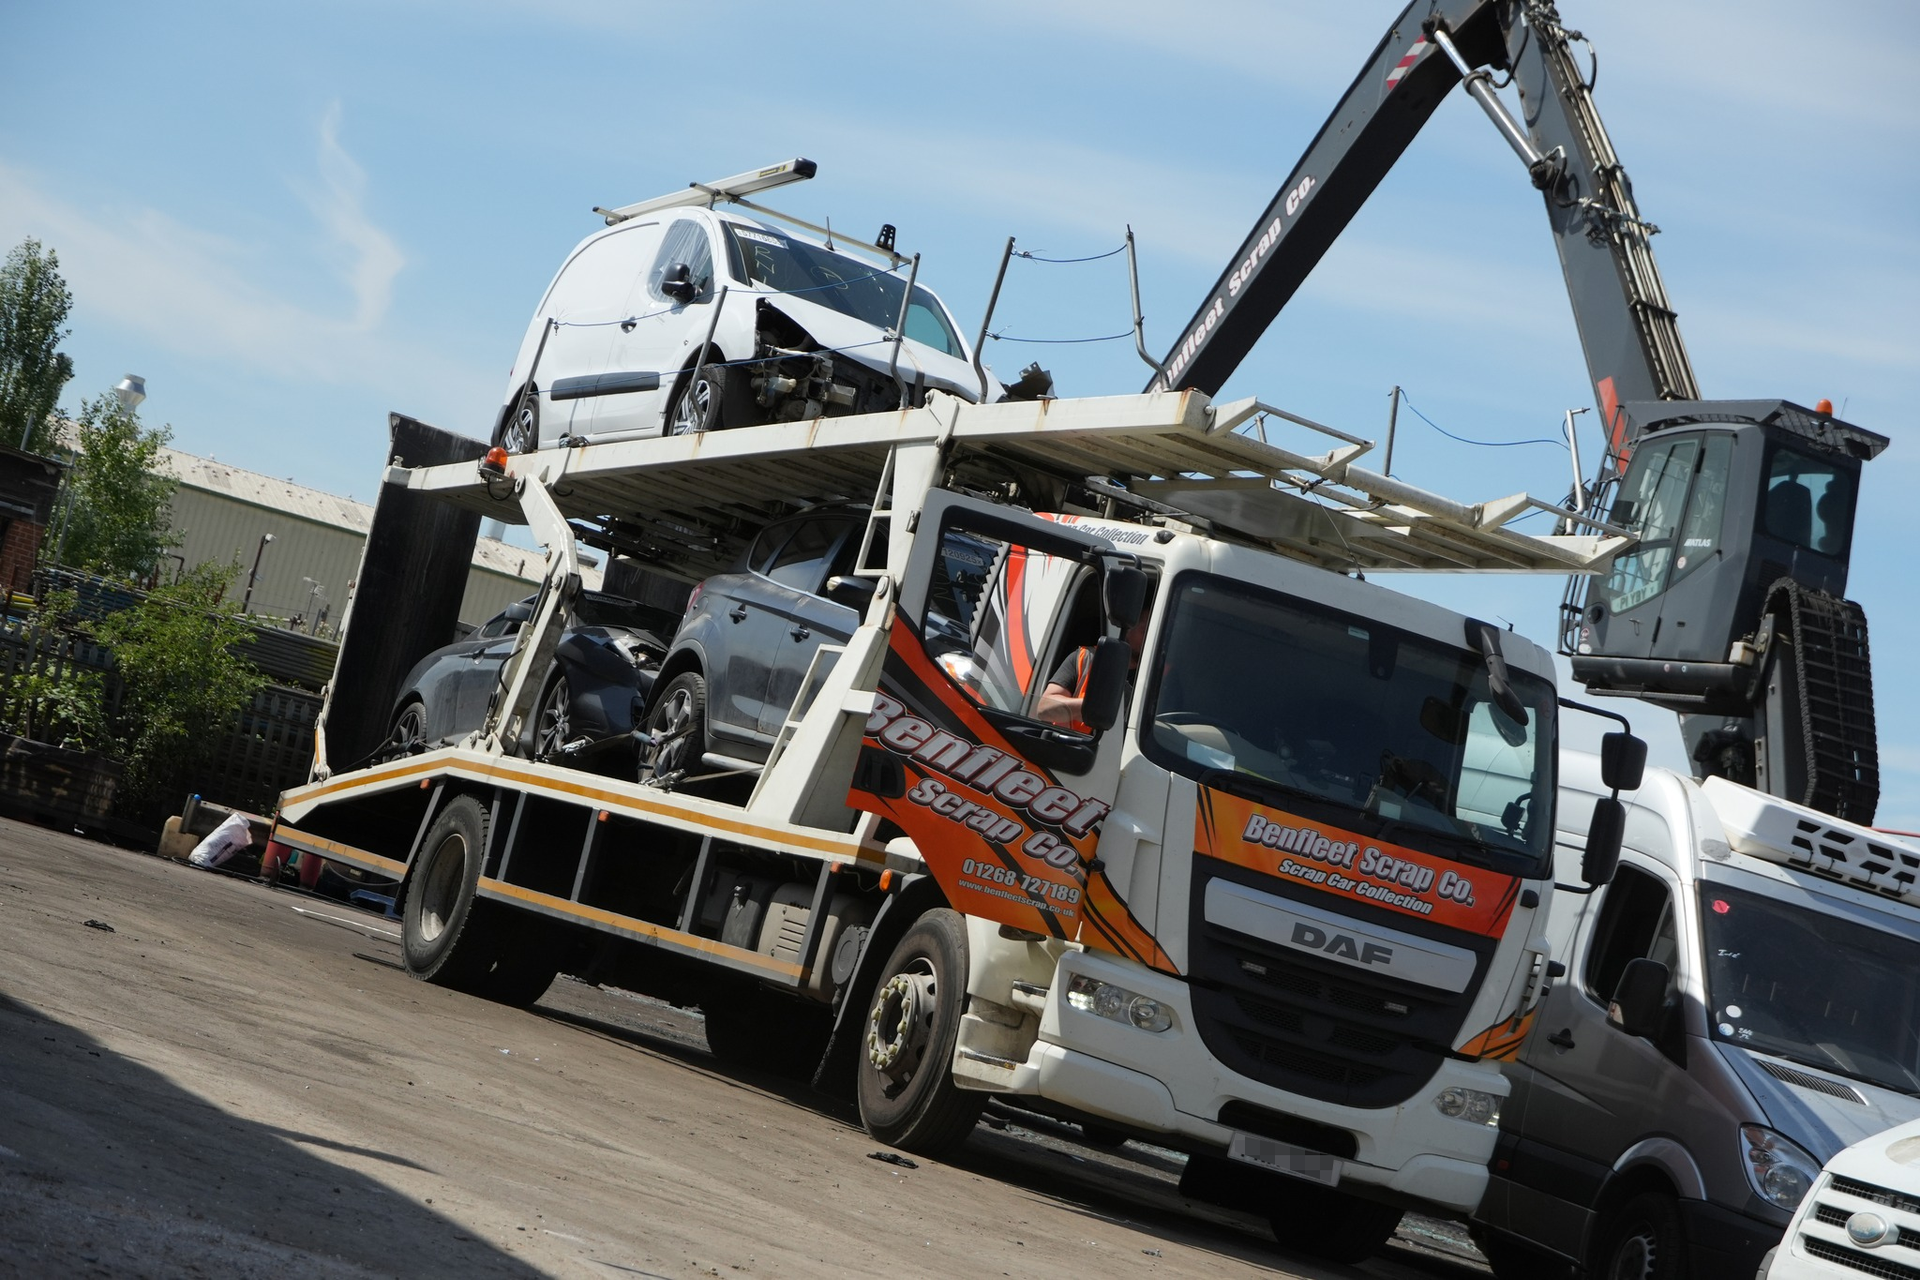
All vehicles are processed through an Authorised Treatment Facility, so you can be confident the scrapping process is fully legal and compliant with UK environmental regulations.
Collection is free across Essex, payments are made directly to your bank account on the same day, and the team is on hand to answer any questions about the process before you commit.
If you want to know how others have found the experience, read what our customers say and see why Benfleet Scrap Co is the most trusted name in scrap car collection across Essex.
Frequently asked questions
Can I scrap a car that's still on a PCP agreement?
You can, but you must get permission from your finance company first. With a PCP agreement, the finance company legally owns the vehicle until the final balloon payment is made. You will need to request a settlement figure and either pay it off or use the scrap payment to contribute towards it before the car can be legally scrapped.
What happens if I scrap a car I don't legally own?
Scrapping a car you do not legally own, without the owner's consent, can be treated as fraud. If the vehicle is on a PCP or HP agreement, the finance company is the legal owner. Disposing of their asset without authorisation could lead to criminal charges and will not remove your obligation to repay the outstanding debt.
How do I find out if my car has outstanding finance before scrapping it?
The most reliable method is to run an HPI check using your vehicle's registration number. This costs between £10 and £20 and will confirm whether any finance is registered against the vehicle. If you already have an active finance agreement, contact your lender directly to get the current settlement figure.
Will the scrap money cover my remaining finance balance?
It depends on the vehicle and what you owe. If the scrap value exceeds your settlement figure, you will clear the debt and receive the difference. If the balance is higher than what the car is worth in scrap, you will need to cover the shortfall. Getting an instant quote first gives you clarity before you speak to your lender.
Do I need to tell my finance company before arranging scrap collection?
Yes. If your car is on PCP or HP, you must contact your finance company before arranging collection. Scrapping the vehicle without their knowledge or consent could be considered fraudulent. Call your lender, explain the situation, and request a settlement figure before taking any further steps.
Can Benfleet Scrap Co collect a car that has finance on it?
Benfleet Scrap Co can collect and scrap a financed vehicle once the finance company has confirmed the settlement has been agreed or paid. The team is experienced in handling these situations and can walk you through the process. Same-day bank payments mean that the proceeds from scrapping can be used to settle the balance quickly and efficiently.
What documents do I need when scrapping a car with outstanding finance?
You will typically need your V5C logbook, a valid form of photo ID, and written confirmation from your finance company that the settlement has been agreed or cleared. Benfleet Scrap Co will issue a Certificate of Destruction once the vehicle has been processed, which you should then use to notify the DVLA.
Ready to take the next step? Scrap your car with Benfleet Scrap Co and get a same-day bank payment, free collection across Essex, and the support of a trusted family business that has been doing this for over 40 years.
If you have already gone through this process yourself, we would love to hear about your experience. Leave a review or share it on social media to help other Essex drivers know what to expect.
If you have a question about this blog (or any of our other blogs) then please do not hesitate to get in touch.
We will always try and answer your question quickly and professionally.